October Is the New December: A Year-End Tax Planning Playbook for Medical Professionals
Your calendar probably does not have a square labeled “think about taxes.” It has patients to see, charts to finish, shifts to cover, and perhaps a practice to run. If you’re a physician, dentist, nurse practitioner, physician assistant, CRNA, pharmacist, or another healthcare professional, year-end tax planning can feel like one more task competing for the same limited time.
But October offers something December often does not: room to make decisions deliberately.
By the time your tax preparer sees your documents next spring, many choices that affect your 2026 return will already have been made. Your retirement-plan elections may be locked in. A planned charitable gift may or may not have happened. A year-end bonus may have arrived without enough tax withheld. And if you also earn 1099 income from locum tenens work, consulting, expert-witness work, or a side practice, your W-2 withholding may not tell the whole story.
This is not a call to make every possible tax move. It is a call to identify which decisions actually apply to you, put them in the right order, and leave enough time to act.
The best year-end tax strategy is not necessarily the one with the most deductions. It is the one that fits your income, benefits, family, and long-term plan.
Start with a projection, not a checklist
Before changing an investment or increasing a contribution, estimate where your 2026 income will land. For a medical professional, last year’s return may be a poor guide. You may have changed employers, completed training, taken on additional shifts, received a production bonus, started consulting, or reduced your hours. If you own a practice, business income can move substantially from one year to the next.
Combine your expected wages, bonuses, practice profits, 1099 income, your spouse’s income, and investment income. Then subtract what you have already paid through withholding and estimated payments. Compare a few plausible year-end outcomes before choosing deductions or conversions. Gather your latest pay statements, year-to-date retirement contributions, 1099 income and expenses, investment gains and losses, and any planned charitable gifts, and ask your tax professional to model the result.
The IRS offers two useful starting points: the Tax Withholding Estimator and Publication 505, Tax Withholding and Estimated Tax.
The projection does not have to be perfect to be useful. Its job is to show whether you are heading toward an unexpected balance due, whether a contribution could meaningfully change your tax picture, and whether a Roth conversion or charitable gift deserves a closer look.
| If your 2026 income changed because… | Investigate… |
|---|---|
| You took a new hospital or group-practice job | Retirement-plan elections, employer contributions, and total deferrals across jobs |
| You earned locum tenens or consulting income | Estimated taxes, deductible business expenses, and self-employed retirement options |
| You expect a large bonus or unusually high practice profit | Withholding, tax-bracket effects, and the timing of discretionary decisions |
| You reduced hours or retired | Whether a lower-income year creates a useful Roth-conversion opportunity |
| Your household changed health plans | HSA eligibility, contributions, and coordination with a spouse’s FSA |
The point is not to treat every row as a recommendation. It is to decide where a few hours of planning could make a difference.
Check retirement contributions across all your jobs
Healthcare careers often involve more than one employer. A physician might have a hospital position and a separate consulting business. A nurse practitioner might change health systems during the year. A dentist might split time between an employed role and a practice. That can make retirement-plan limits less intuitive than they appear on a benefits portal.
For 2026, the general employee elective-deferral limit for 401(k), 403(b), and most governmental 457(b) plans is $24,500. Participants age 50 or older may have an $8,000 catch-up, and eligible participants ages 60 through 63 may have a higher $11,250 catch-up, if the plan permits it. (IRS: 2026 retirement-plan limits; IRS: Catch-up contributions)
Here is the part that surprises people: employee deferrals to 401(k) and 403(b) plans generally share one individual limit across all your employers, while an eligible governmental 457(b) generally has a separate limit. A second job does not automatically give you a second full employee limit. Verify plan provisions and any employer contributions instead of assuming. If you changed jobs in 2026, check what you contributed at your former employer before setting a year-end election at your current one. Each payroll department sees only its own plan.
There is another reason to review your election now. Beginning in 2026, certain employees whose prior-year wages from the sponsoring employer exceeded $150,000 may be required to make catch-up contributions as Roth contributions. That rule concerns the catch-up portion, not the regular deferral limit. Confirm with payroll and your plan how it applies to you.
IRAs, HSAs, and the calendar
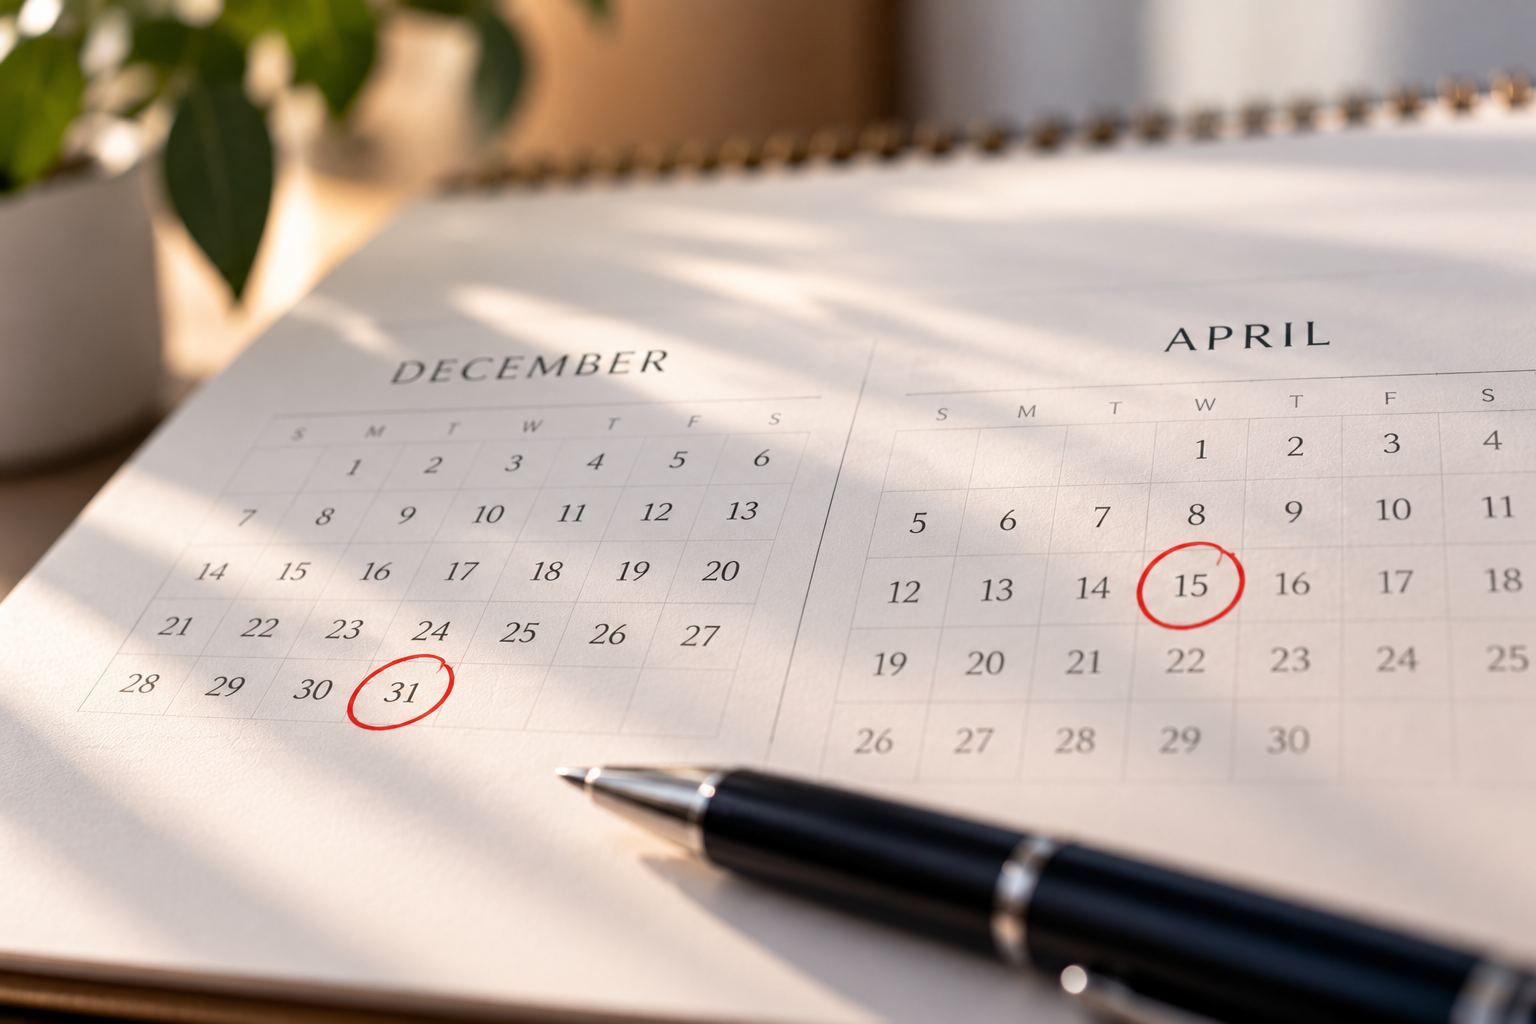
Not every contribution has the same deadline, and mixing them up is a common October mistake.
Workplace salary deferrals generally require action through 2026 payroll. If you want to change an election, ask when payroll’s cutoff is. It may be well before December 31.
IRA contributions for 2026 are limited to $7,500, plus $1,100 if you are 50 or older, subject to eligibility and income-related deduction and Roth rules. (IRS: IRA contribution limits; Publication 590-A)
HSA contributions for 2026 are reported at $4,400 for self-only and $8,750 for family coverage, with a $1,000 catch-up for an eligible account holder age 55 or older. Please confirm the amounts against current IRS material before relying on them. (Publication 969)
Eligible 2026 IRA and HSA contributions generally can be made until April 15, 2027, without extensions. That flexibility is helpful, but it should not become a reason to skip the projection. HSA eligibility also requires more than a high-deductible plan on paper: Medicare enrollment or other disqualifying coverage can affect it, and a spouse’s health FSA can complicate things.
If you have W-2 income and 1099 income
Many clinicians have a W-2 job and a side income stream. The W-2 job withholds tax from each paycheck. The 1099 work usually does not.
Additional independent-contractor income can create both income tax and self-employment tax. If nobody is withholding on it, the shortfall can surface in April, sometimes with an underpayment penalty. Rather than guessing from your W-2, estimate your whole-year liability and then check it against the estimated-tax safe harbors.
Generally, you can avoid an underpayment penalty by paying at least 90% of your current-year tax or 100% of your prior-year tax. The prior-year figure rises to 110% if your prior-year AGI exceeded $150,000 ($75,000 if married filing separately). Exceptions and installment rules apply. (Publication 505; Form 1040-ES; Form 2210)
Timing matters, too. Withholding is generally treated as paid evenly throughout the year for underpayment calculations, but a late estimated payment is not automatically treated the same way. That makes October a useful time to ask whether raising W-2 withholding, rather than writing a large estimated payment later, would fit your situation. The fourth 2026 estimated-tax installment is generally due January 15, 2027.
If you have a side business, also keep records that support your business expenses, and talk with a tax professional about entity structure and state tax.
Roth decisions: useful, but not automatic
A Roth conversion moves pre-tax retirement money into a Roth account, and the converted amount can add taxable income in 2026. It may also affect other income-sensitive calculations. A lower-income year, perhaps because of reduced hours, a gap between jobs, or retirement, can make a conversion worth considering. A high-income year may point the other way.
The so-called “backdoor Roth” is not automatically tax-free either. Nondeductible traditional IRA basis, along with balances in traditional, SEP, and SIMPLE IRAs, matters under the aggregation and pro-rata rules. Work through the numbers with the projection first, and review the Form 8606 instructions and Publication 590-A. A conversion is a decision about your whole plan, not a benefit you collect for free, so no one should promise that it will help.
Charitable giving: plan the gift, not just the deduction
If you give regularly, compare a few approaches: itemizing as usual, bunching several years of gifts into one tax year, or donating appreciated investments where appropriate instead of cash. Which works best depends on whether you itemize at all, which is why the projection comes first.
A qualified charitable distribution (QCD) is different. It generally requires an eligible IRA owner age 70½ or older, a direct qualifying transfer from the IRA to the charity, and satisfaction of other conditions. A QCD is not also a charitable deduction. A limited deduction for qualifying cash gifts by taxpayers who do not itemize begins in 2026, but check current eligibility, caps, and reporting guidance before you plan around it. (IRS: Qualified charitable distributions; Publication 526)
Investments: look before you sell
Review your gains, losses, concentrated positions, and tax lots before you sell anything. Net capital losses generally offset capital gains and then up to $3,000 of other income per year ($1,500 if married filing separately), with remaining losses carried forward.
Watch the wash-sale rule. A loss on stock or securities can be disallowed if you acquire substantially identical securities within 30 days before or after the sale. A repurchase in early January, or an automatic reinvestment in December, can undo a loss you thought you had locked in. (Publication 550; IRS Topic 409)
Benefits and medical expenses
Unreimbursed qualifying medical expenses generally produce an itemized deduction only to the extent they exceed 7.5% of AGI, so many households will not benefit. Avoid double-counting costs that were reimbursed by insurance or paid from tax-favored accounts. (Publication 502)
Also check your health FSA. Spending, grace-period or carryover, and claim-submission deadlines depend on your employer’s plan, and may not match the tax filing deadline. Ask your benefits team for the dates in writing. (Publication 969)
Your October checklist
You do not have to do everything on this list. You do have to know which items are yours, and October is a good time to find out. If you would like help sorting that out, you can schedule an introductory Fit meeting with our team.
Book an introductory Fit meeting
We will assess mutual fit, build rapport, and share information about our firm and pricing to confirm next steps.
DISCLAIMER
General information only. This content is for educational purposes and is not individualized tax, legal, or investment advice. Tax rules, limits, and eligibility depend on your facts and on the terms of your employer plans, and may change. Consult a qualified tax professional about your situation before acting.